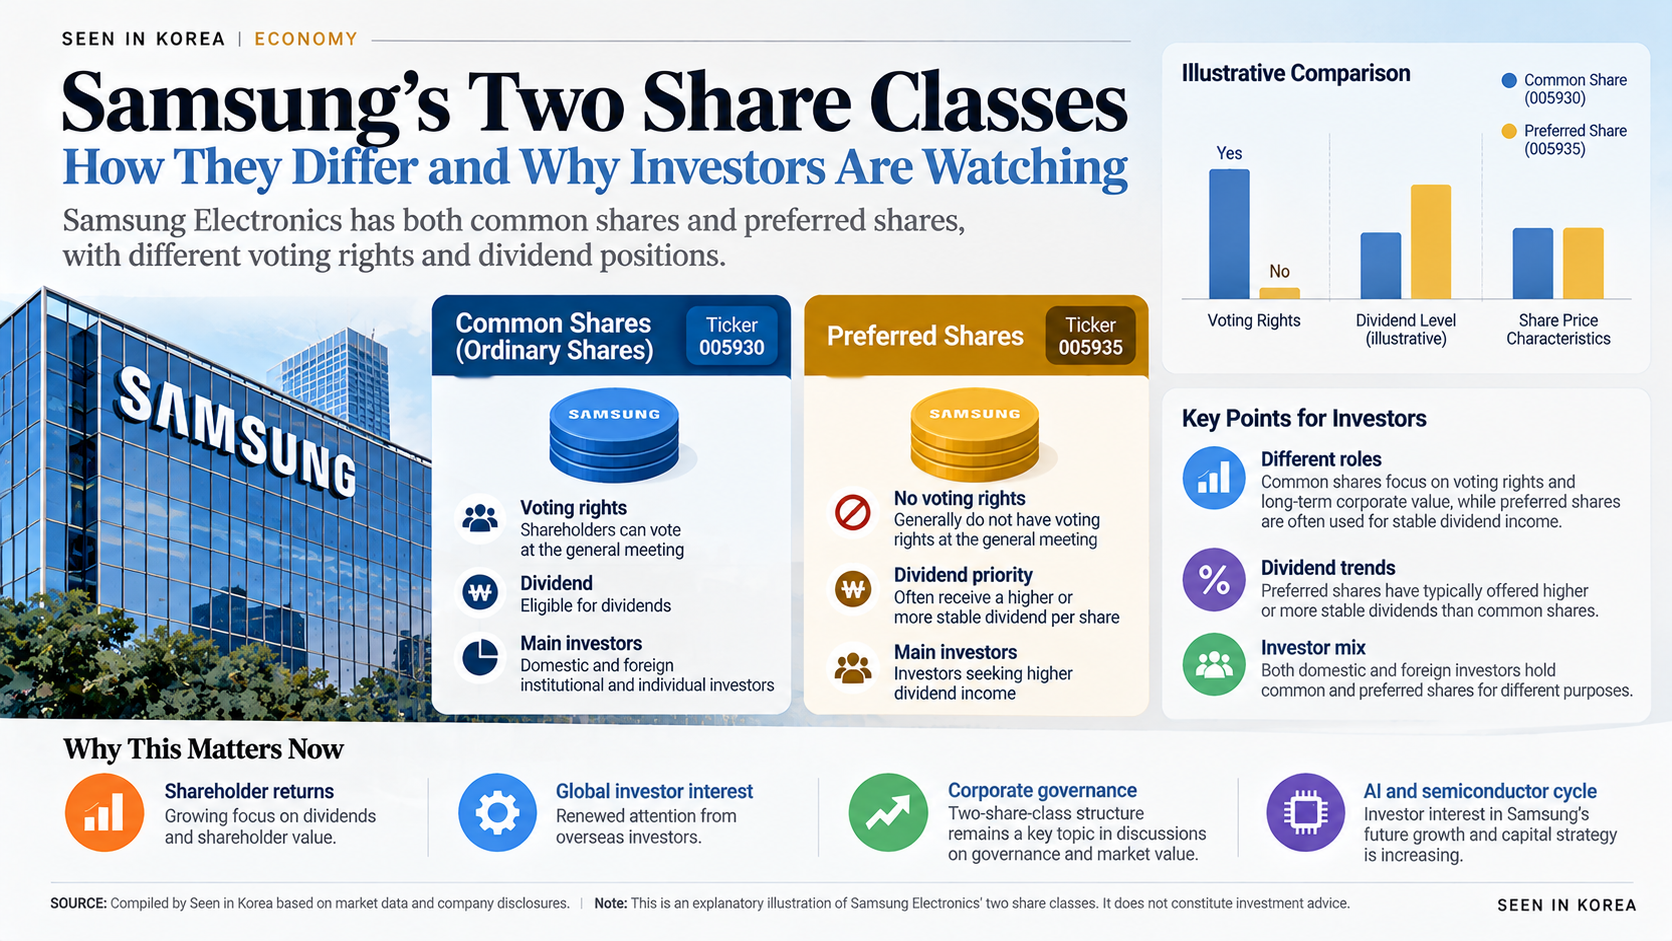
Samsung Electronics' non-voting preferred shares have become the focus of a debate about whether Korean companies can improve capital efficiency without creating new conflicts between investors. London-based activist Palliser Capital wants Samsung to address the valuation gap between preferred and ordinary shares. This is an investor proposal—not a decision that Samsung's board has accepted.
What happened
Reuters Breakingviews reported a roughly 23% preferred-share discount on October 27, while an October 28 report in Seoul Economic Daily cited a 26% discount estimate attributed to Palliser. These are observations from different sources and times, not a fixed contractual discount. Palliser has urged Samsung to buy back and cancel preferred shares, according to Reuters Breakingviews. The activist has proposed an approach including substantial preferred-share purchases and the possible use of US American Depositary Receipts, or ADRs, to support financing.
Palliser's estimates and desired outcomes should be attributed to Palliser. They are not financial results announced by Samsung and they do not show what shareholders will actually earn.
The number that matters
The 23% Reuters figure, and the separate reported 26% figure, are market snapshots rather than promises that the gap will persist. Preferred shares may offer different voting and economic rights from common stock, so prices need not match. A discount can reflect liquidity, investor preferences and expectations about future cash flows. It cannot, by itself, establish that a share is undervalued or that an investment is attractive.
Reuters described an activist proposal involving approximately KRW 132 trillion in preferred-share buybacks and a long-term goal of retiring the class by 2028. That is the scale of the activist's proposed course, not a board-authorized repurchase programme. Samsung's separate August corporate announcement on 2026 shareholder returns must not be blended into Palliser's proposal.
Why it matters in Korea
Korean conglomerates often face questions about how voting control, cash distributions and minority rights are balanced. An activist proposal targeting only preferred shares could prompt debate over whether ordinary shareholders are being treated equitably. It also raises practical questions about funding, liquidity and the effects of reducing one class of stock.
A more complete examination of capital allocation would compare such a proposal against alternatives including dividends, proportional repurchases, investment in future production and reduced debt. Management must weigh interests that do not always line up.
Why it matters globally
International investors use preferred and ordinary shares differently, and some hold Korean companies through overseas instruments or indices. The outcome therefore offers a window into how a global company responds to foreign activism while operating within Korea's corporate governance system. It is not evidence that Korea has already reformed its preferred-share regime.
What could change
Samsung could reject, modify, study or adopt portions of an activist plan. Regulatory, tax, governance and investor-approval questions may be material. Future market prices could also narrow or widen the reported discount irrespective of any corporate action.
Preferred shares and ordinary shares are not interchangeable
A non-voting preferred share may offer different rights, liquidity and investor protections from an ordinary share. Even where economic entitlements are similar, the absence of voting rights can affect what investors will pay. Therefore the presence of a discount does not by itself prove a market malfunction or identify its correct size. A numerical comparison must specify the observation date and the securities compared.
Repurchases also have distributional effects. If a corporation buys back one class of shares rather than another, remaining holders of each class may experience different outcomes. Some investors might welcome closing the gap, while others could object to a transaction they regard as uneven. Activist presentations naturally focus on the potential benefits of their preferred approach; the company's directors must evaluate costs and fairness across shareholders.
Issuing ADRs would introduce another layer. An ADR represents a tradable depositary interest and can broaden access for overseas investors, but the structure may involve fees, custody arrangements, regulatory disclosure and market demand. It should not be treated as a costless way to finance buybacks. Until the company makes a formal decision, all such measures belong in the category of proposals.
What the latest price move does and does not show
On October 28, Korean market coverage described an outsized gain in Samsung's preferred shares as debate over buybacks intensified. That does not show that Samsung accepted Palliser's request. Equity prices change continuously, so any percentage discount belongs to the observation date and share-price pair used in the calculation. An activist's estimate of value creation is likewise a scenario based on assumptions, not a guaranteed shareholder return.
A formal corporate response, if issued, will matter more than a short-term price move. The strongest evidence would be an actual board resolution describing which share class is eligible for repurchase, how much funding is committed, whether purchases would be cancelled and what approvals are required.
What we're watching
Samsung's official board disclosures, any detailed Palliser proposals, responses from ordinary and preferred shareholders, and whether the company announces actual repurchases and cancellations. The story is a governance debate, not a recommendation to buy either class of stock.
- Reuters Breakingviews — Palliser buyback proposal and 23% snapshot, Oct. 27
- The Korea Herald — Palliser proposal and ADR discussion, Oct. 14
- Seoul Economic Daily — October 28 preferred-share price and 26% claim
- Samsung Electronics — official shareholder return plan, Aug. 21
- Dalton Investments — separate Oct. 15 shareholder statement (not a Samsung decision)